Stage 10 of 14Extreme concentrationHard to substitute
Chapter 10: Advanced Packaging
Epoch AI estimates that in 2025 Nvidia, Google, AMD and Amazon used around 90 percent of the capacity for CoWoS, TSMC’s packaging for AI chips.
Sharma, Yashvardhan. “Advanced Packaging.” Chip Supply Chain: How AI Chips Are Made. Updated 29 October 2026. https://chipsupplychain.org/advanced-packaging/
A CoWoS-L package, pulled apart. Two logic dies and eight HBM stacks sit on the interposer, shown in silver with its copper wiring. In CoWoS-L the interposer is fine redistribution wiring with small embedded silicon bridges. It sits on a resin substrate with a grid of solder balls underneath. The chips together cover about 2,700 mm², a little over three reticle fields. Footprints are to scale. Thicknesses and the gaps between layers are exaggerated.
Parts, as numbered on the drawing
- 1Logic dies, two: see stage 08, Foundries and Fabs
- 2HBM stacks, eight: see stage 09, Memory and HBM
- 3Interposer: TSMC (TW), as CoWoS
- 4Substrate: see stage 11, Substrates and PCBs
In plain terms
Packaging joins finished into one component and mounts them on a small , called a , wired far more coarsely than the chips themselves. A , which prints a chip’s circuits, can cover only a rectangle about the size of a postage stamp in one shot. Many leading , Nvidia’s Blackwell among them, need more logic than fits in that rectangle. So they are built from several chips, called , set side by side on an , a layer of much finer wiring that links them and sits on the substrate. Stacks of memory chips sit on the same interposer, a few millimeters away. The interposer is either one piece of silicon or layers of fine copper wiring that often carry small where the links are densest. Silicon expands less than the resin substrate beneath it when heated, so the package can warp and its joints crack. Preventing that in is hard. Nvidia, Google, AMD and Amazon all use TSMC’s interposer packaging, called , made in Taiwan.
In short
Epoch AI estimates that in 2025 Nvidia used 60.3 percent of all capacity for , TSMC’s packaging1. On the July 2026 earnings call, TSMC’s chief executive, C.C. Wei, said its packaging capacity was so tight that it limited customers’ growth2. Asked about Intel’s -T packaging, he said he hoped it would take some of the load off TSMC2.
In a TrendForce ranking by 2024 revenue, which CSET cites, four of the top ten outsourced firms that package and test are headquartered in China3. But in 2025 Chinese firms had 5.3 percent of the market for fabrication tools, against 65.8 percent for US firms, by CSET’s analysis of TechInsights data4.
A prints a rectangle 26 mm by 33 mm, or 858 , in one exposure5. That area is called the . Every leading , counting its , covers more area than that. Packaging is the stage that lets an accelerator be larger than one reticle field, and the packaging method limits how much larger it can be.
- Who leads
- TWTSMC CoWoS packaging used by Nvidia, Google, AMD and Amazon in 20251
- USIntel Foveros 3D packaging in volume at Rio Rancho, New Mexico, since January 20247
- TWASE Technology NT$389.2 billion assembly, test and materials revenue, 20258
- USAmkor $6.71 billion net sales, 20259
- CNJCET RMB 38.87 billion revenue, 202510
- SGASMPT Thermocompression bonders, with $532.1 million of advanced packaging revenue in 202511
- Where it is made
- TWTaiwan TSMC advanced packaging fabs and a cluster of outsourced assembly and test firms
- USUnited States Intel Foveros packaging in volume at Rio Rancho, New Mexico
- CNChina Four of the top ten outsourced assembly and test firms by 2024 revenue are Chinese, in a TrendForce ranking cited by CSET
- NLNetherlands Besi hybrid bonders
- JPJapan Disco grinders and dicers
- Why substitution is slow
- CoWoS packaging has been outsourced to assembly firms such as ASE and Amkor before12. Intel’s , which links through silicon bridges embedded in the , is another option, and Amazon’s Trainium and Google’s were both adopting it as of March 202612. But a newcomer would have to match TSMC, which said in April 2026 that it was producing CoWoS at 5.5 times the area a prints in one shot13.
Chinese firms had 5.3 percent of the market for fabrication tools built for in 2025, by CSET’s analysis of TechInsights data4. Between 2019 and 2024 they gained 5 percentage points of share in test tools but lost share in bonding and other conventional assembly and packaging tools3.
How advanced packaging and CoWoS work
A second reason for the is high bandwidth memory (HBM). An HBM4 stack connects through 2,048 data signals, packed too tightly for a standard , so the memory sits beside the logic on the interposer15. Even Nvidia’s H100, whose single is 814 mm² and fits inside one reticle field, carries five HBM stacks16. Epoch AI counts TSMC’s packaging among the three inputs the H100 needs, along with its logic die and its HBM1.
The parts of an AI accelerator
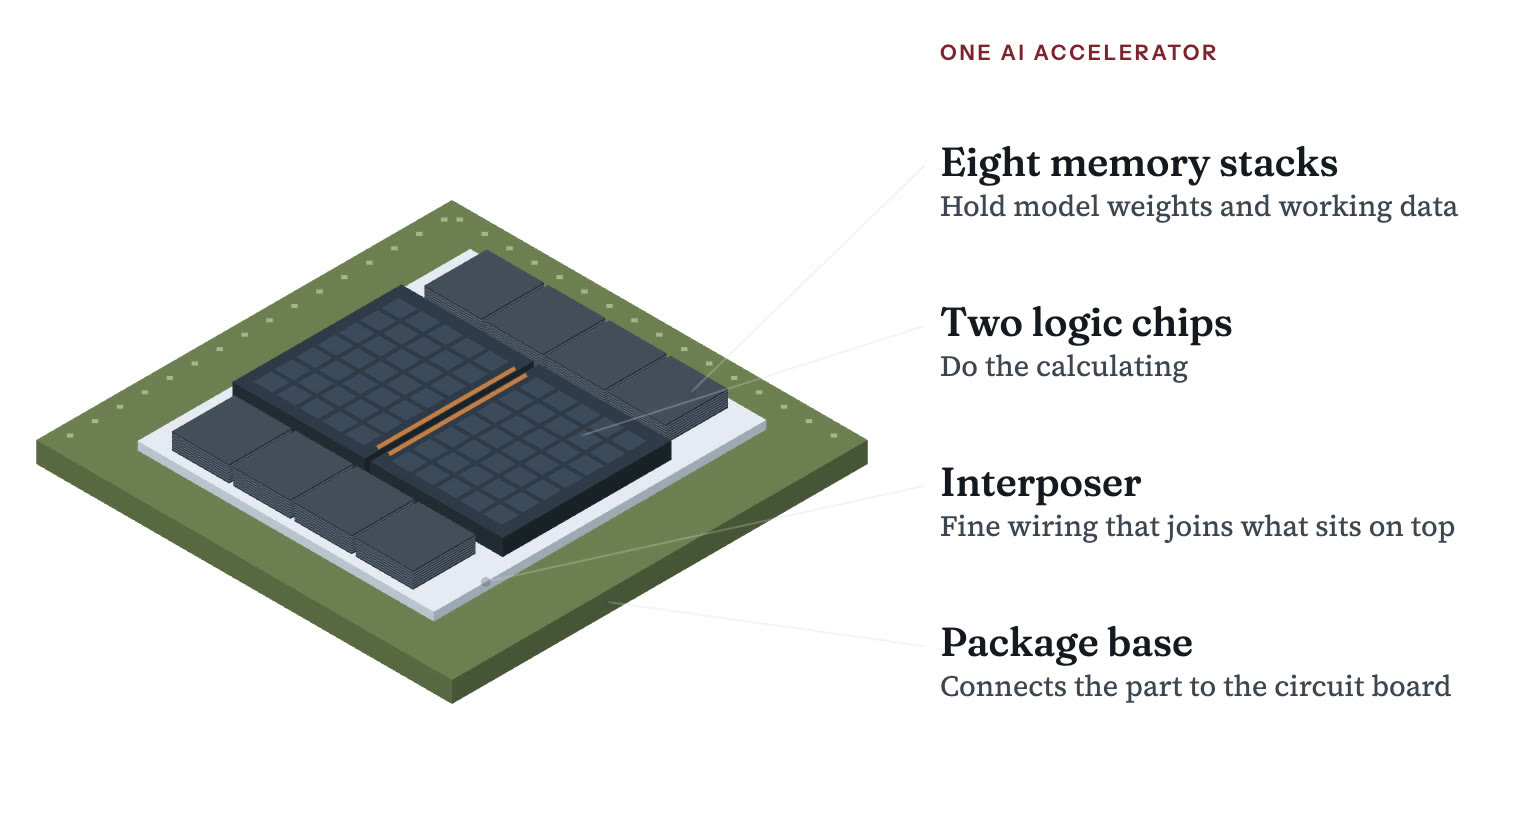
- Package base. An AI chip is built from several parts. First comes the package base, a layered board that connects everything to the circuit board below.
- Interposer. On it sits an interposer, a thin layer of very fine wiring that joins everything placed on top.
- Logic chips. Two logic chips go in the middle. They do the calculating, and each is as large as a chipmaking machine can print.
- Memory. Eight stacks of memory go beside them, a few millimeters away. They hold the AI model’s weights and the record of each conversation so far.
- One package. Together they make one AI accelerator. Most are put together by TSMC, in Taiwan.
CoWoS stands for chip on wafer on substrate, the order in which the parts are joined. For CoWoS-S, the version whose interposer is one piece of silicon, TSMC makes a that carries wiring and but no . Vias are metal-filled holes that join one layer of wiring to the next.
TSMC bonds the logic dies and memory stacks face down onto that wafer with . These are dots of solder, and each dot is one electrical joint. In Intel’s Foveros , which can also set side by side on a silicon interposer, the microbumps sit 36 apart, less than half a hair’s width17. The spacing differs by design, and SK hynix gives about 20 micrometers as typical for microbumps18. Then TSMC cuts the interposer out of the wafer and attaches it to the resin substrate, which later goes onto a .
One cracked joint can scrap a package holding eight tested HBM stacks and two large, expensive logic dies. Epoch AI estimated in December 2025 that CoWoS-L packaging, the version built with small , added about $1,100 to the cost of building one Nvidia B2006. That is more than its estimate of about $900 for the B200’s two logic dies6. Epoch AI adds about $1,000 more to each B200 for the packages that fail testing, whose logic dies and memory stacks are lost6.
Types of advanced packaging
| Family | Carrier | Size limit | Used for |
|---|---|---|---|
| CoWoS-S | Full silicon interposer | Up to 3.3× | H100-class parts |
| CoWoS-R | Resin interposer with fine | Above 3.3× reticle | Cost-sensitive, fewer HBM stacks |
| CoWoS-L | Redistribution wiring with local silicon bridges | 5.5× reticle in production, 9.5× in development | Blackwell |
2.5D: silicon, RDL and bridges
In 2.5D packaging the sit side by side and connect through an interposer or silicon bridges beneath them. TSMC has run CoWoS since 201219. CoWoS-S has the finest wiring, but its interposer is one unbroken piece of silicon whose (the share of interposers that work) falls as the area grows. CoWoS-L replaces that piece of silicon with redistribution layers (RDL) of fine copper wiring and embeds small silicon bridges where the wiring is densest20.
Intel’s EMIB embeds similar silicon bridges in the resin substrate17. SemiAnalysis reported in March 2026 that EMIB was gaining traction, with Amazon’s Trainium and Google’s both adopting it12.
Blackwell was the first high-volume design on CoWoS-L, and packaging problems at TSMC and in Nvidia’s design limited its supply21. The bridges that carry the 10 link between the two logic dies must be placed very precisely21. The dies, bridges, interposer and substrate also expand at different rates, and that mismatch caused warpage21.
3D: SoIC and Foveros
In 3D packaging one die sits on top of another, and the joints between them are moving from solder microbumps to . Intel’s Foveros stacks dies face to face and joins them with solder microbumps17. Its newer Foveros Direct drops the solder and bonds the copper pads directly, a method called hybrid bonding17. Hybrid bonding joins the around the pads as well as the copper, with no bumps in between18. That lets the connections sit far closer together than microbumps allow17. TSMC’s SoIC also uses hybrid bonding, and AMD’s 3D V- processors use SoIC to attach an extra cache die to the processor die22. Stacking also changes how power reaches the top die, which has to draw it up through vertical wires in the die below, called (TSVs)22.
TSMC put SoIC into volume production in 2022, stacking SRAM memory chips on logic wafers23. Its 3 nm SoIC entered volume production in 202520. An A14-on-A14 version, stacking dies made on TSMC’s 1.4 nm process, is due in 202913. It will carry 1.8 times the die-to-die connection density of SoIC that stacks 2 nm dies on 2 nm dies13.
SoIC bonding also brings optics into the package. TSMC’s COUPE uses SoIC to join a silicon photonics chip, which sends data as light, to its electrical control chip20. In April 2026 TSMC planned to begin producing COUPE on substrate later that year13. It also said that putting COUPE inside the package gives twice the power efficiency of a pluggable version on the circuit board13.
Two ways off the silicon interposer
builds packages on a large rectangular panel instead of a round wafer, so rectangular packages fit it with less waste at the edges. See Test and assembly. , the semiconductor standards body, published a standard called SPHBM4 on 13 July 2026. It puts HBM4 memory on a carrying 512 data signals instead of 2,048, each running four times as fast to keep the same bandwidth15. With fewer signals, the connections can be spaced widely enough to mount the stack on a standard resin substrate instead of the silicon interposer15.
TSMC’s CoWoS capacity and its buyers
TSMC does not publish its CoWoS capacity1. Industry estimates from SemiWiki and TrendForce, compiled by Epoch AI, put it at about 65,000 to 75,000 at the end of 2025, up from 35,000 to 40,000 a year earlier1.
On the July 2024 earnings call, TSMC’s chief executive, C.C. Wei, said TSMC was more than doubling CoWoS capacity in 2024 and would more than double it again in 202524. He said he could not yet balance supply and demand24. At its 2024 symposium TSMC had said CoWoS capacity would grow at a 60 percent compound annual rate over the next few years24. Asked about that rate on the call, Wei did not repeat it24.
In October 2025 Wei would say only that TSMC was still working to increase CoWoS capacity for 2026, and he gave no figure25. He said capacity (making the chips) and capacity (packaging them) were both, in his words, very tight25.
By Epoch AI’s estimate, four chip designers used most of the world’s CoWoS capacity in 2025 but only a small share of its advanced chipmaking. Epoch AI compared each chip designer’s use of components with world supply1. It puts Nvidia at 60.3 percent of all CoWoS capacity in 2025, with a 90 percent confidence interval of 56.5 to 64.31. Google took 13.5 percent, AMD 8.4 and Amazon 7.41. The four also used around 90 percent of global HBM supply in 2025, measured by value1. But they used only 12 percent of advanced logic die production1.
Nvidia used an estimated 60.3 percent of CoWoS capacity in 2025
Estimated share of CoWoS capacity used, 2025
| Nvidia | 60.3% |
|---|---|
| 13.5% | |
| AMD | 8.4% |
| Amazon | 7.4% |
| Everyone else | 10.4% |
Sharma, Yashvardhan. “Figure 10.2: Estimated share of CoWoS capacity used, 2025.” Chip Supply Chain: How AI Chips Are Made. Updated 29 October 2026. https://chipsupplychain.org/advanced-packaging/#fig-advanced-packaging-cowos-buyers. Data: Epoch AI, advanced packaging and HBM were the bottlenecks on AI chip production in 2025, 12 March 2026.
In March 2026 the research firm SemiAnalysis judged that front-end capacity had become the dominant bottleneck and that CoWoS constraints were easing12. It said TSMC was planning CoWoS capacity around how many wafers N3, its 3 nm process, could produce, because added packaging capacity is of no use without front-end wafers to fill it12.
TSMC gave a different account four months later. On the July 2026 earnings call, Wei said back-end capacity was still in shortage26. Asked about Intel’s EMIB-T, he said he welcomed the extra flexibility and hoped it would take some of the load off TSMC2.
Who makes advanced packages
TSMC plans 14-reticle CoWoS interposers for 2028, up from 3.5 in 2024
CoWoS interposer size on TSMC’s roadmap
| 2024, CoWoS-L | 3.5 reticles |
|---|---|
| 2026, in production | 5.5 reticles |
| In development, no date | 9.5 reticles |
| 2028 | 14 reticles |
Sharma, Yashvardhan. “Figure 10.3: CoWoS interposer size on TSMC’s roadmap.” Chip Supply Chain: How AI Chips Are Made. Updated 29 October 2026. https://chipsupplychain.org/advanced-packaging/#fig-advanced-packaging-cowos-reticles. Data: TSMC 2025 annual report and 2026 technology symposium, 23 April 2026.
Three kinds of firm package chips. TSMC, which makes chips for others, and Intel, which makes its own, do it in their own back-end fabs. firms do the rest. Intel opened 9 in Rio Rancho, New Mexico, in January 2024 to make its Foveros 3D packages in volume7. It called the plant the only US factory producing the most advanced packaging at scale7.
ASE leads the outsourced assembly and test firms, and Amkor is the largest one headquartered in the United States. ASE Technology Holding had revenue of NT$645.4 billion in 2025, about 40 percent of it from its electronics manufacturing arm, a business separate from assembly and test8. Its assembly, test and materials business brought in NT$389.2 billion, up from NT$325.9 billion in 20248. Amkor had net sales of $6.71 billion in 20259.
Each of the key packaging tools comes from a small number of makers.
- . Pressing dies together under heat and force. ASMPT’s advanced packaging revenue reached $532.1 million in 2025, with thermocompression bonder revenue up about 146 percent11. ASMPT targets 35 to 40 percent of a market it puts at $1.6 billion in 202811.
- Hybrid bonding. Copper pads and the insulator around them bond directly, with no solder. Applied Materials co-developed its Kinex hybrid bonding system with Besi, which Applied calls the industry leader in hybrid bonding27.
- and dicing. Disco held 87 percent of the $1.9 billion world market for dicing tools in 2025, by CSET’s count from TechInsights data28. The category covers the grinders that thin wafers and the saws that cut them into chips28. See Test and assembly.
TSMC and Amkor both plan advanced packaging plants in Arizona. TSMC’s Arizona commitment reached $265 billion in July 2026 and covers two advanced packaging plants alongside 10 fabs29. Amkor started building a $7 billion campus in Peoria, Arizona, in October 2025 and expects production from early 202814. The US Commerce Department awarded Amkor up to $407 million in funding for the site in December 202430. In October 2025 Wei said a large outsourced packaging partner, which he did not name, was already breaking ground in Arizona31. He said its plant was on an earlier schedule than TSMC’s own two packaging fabs there31.
The chokepoint
Nvidia, Google, AMD and Amazon all use TSMC’s interposer packaging, called CoWoS, made in Taiwan. By Epoch AI’s estimate, those four used around 90 percent of global CoWoS capacity in 20251. In 2024 TSMC was more than doubling CoWoS capacity and still could not keep up with demand24. On the July 2026 earnings call, TSMC’s chief executive, C.C. Wei, said its packaging capacity was so tight that it limited customers’ growth2. CoWoS packaging can be, and has been, outsourced to assembly firms such as ASE and Amkor12.
China-based suppliers held 7 percent of the market for advanced packaging fabrication tools in 2024
China-based suppliers’ share of advanced packaging fabrication tools and three test tool segments, 2024
| Test, linear and discrete | 69% |
|---|---|
| Burn-in test | 9% |
| Advanced packaging fabrication tools | 7% |
| SoC test | 5% |
Sharma, Yashvardhan. “Figure 10.4: China-based suppliers’ share of advanced packaging fabrication tools and three test tool segments, 2024.” Chip Supply Chain: How AI Chips Are Made. Updated 29 October 2026. https://chipsupplychain.org/advanced-packaging/#fig-advanced-packaging-china-backend-tools. Data: CSET, Inside Beijing’s Chipmaking Offensive, 14 July 2025.
Four of the top ten outsourced assembly and test firms by 2024 revenue are headquartered in China, by a TrendForce ranking that CSET cites3. JCET, a leading Chinese assembly and test firm, had record revenue of RMB 38.87 billion in 2025, up 8.1 percent10. JCET says its XDFOI packaging platform has entered high-volume manufacturing with redistribution-layer interposer, silicon interposer and silicon bridge options32. Those are the same three kinds of carrier that TSMC sells as CoWoS-R, CoWoS-S and CoWoS-L.
Chinese firms had a small share of the market for advanced packaging tools in 2024 and 2025, and they lost ground in bonding. In 2024 Chinese firms had 7 percent of the market for advanced packaging fabrication tools3. Between 2019 and 2024, they gained 5 percentage points of share in test tools and 4 points in fabrication tools built for advanced packaging, by CSET’s analysis of TechInsights data3. But they lost share in bonding and other conventional assembly and packaging tools, the category where CSET counts hybrid and thermocompression bonders3. Within the advanced packaging fabrication tools, Chinese firms gained 10 points in and clean tools and 3 points in tools3. They lost 2 points each in and polishing () tools3. CSET’s Chip Explorer, a separate data tool also built on TechInsights data, puts Chinese firms at 5.3 percent of the $6.2 billion world market for advanced packaging fabrication tools in 20254. It puts US firms at 65.8 percent and Japanese firms at 15.3 percent4.
TSMC said in April 2026 that it was producing CoWoS at 5.5 times the size of a reticle field and planning larger versions13. Each generation on TSMC’s roadmap needs a larger interposer.
- 2028. A 14-reticle interposer, about the area of a compact disc, carrying about ten large compute dies and 20 HBM stacks13.
- 2029. More than 14 reticles, plus a 40-reticle System-on-Wafer13. TSMC describes System-on-Wafer as joining different data center chips at the scale of a whole wafer33.
Flashcards
Recall each answer, then turn the card.
Why is an AI accelerator built from several chips in one package?
It needs more logic than a scanner can print in one shot. So several dies sit side by side on an interposer, a layer of fine wiring, with stacks of memory beside them.
Why is packaging hard?
Silicon and the resin beneath it expand at different rates when heated, so the package can warp and its joints crack.
Which company packages the leading AI chips?
TSMC, in Taiwan, with its CoWoS process. Nvidia, Google, AMD and Amazon all use it.
Why has packaging limited how many AI chips can be made?
TSMC could not add CoWoS capacity fast enough to meet demand, even while more than doubling it.
Four things to remember
- Many leading accelerators, Nvidia’s Blackwell among them, need more logic than one chip can hold, so packaging joins several chips and their memory.
- Nvidia, Google, AMD and Amazon all rely on TSMC, in Taiwan, to package their accelerators.
- Packaging was one of the main limits on AI chip output in 2025. In July 2026 TSMC said its packaging capacity was still so tight that it limited customers’ growth.
- No US site yet packages Nvidia-class accelerators with HBM on CoWoS, though Intel makes its own Foveros 3D packages in volume in New Mexico.
Sources (33)
Source tiers A company filings, governments, standards bodies, universities and research institutions. B SemiAnalysis, Reuters, the Financial Times and Nikkei Asia.
- AAdvanced packaging and HBM, not logic dies, were the bottlenecks on AI chip production in 2025
- AQ2 2026 Taiwan Semiconductor Manufacturing Co Ltd Earnings Call (Chinese, English) — edited transcript
- AInside Beijing’s Chipmaking Offensive
- ASupply Chain Explorer: Advanced Chips
- ATWINSCAN NXE:3400C
- ANVIDIA’s B200 costs around $6,400 to produce
- AIntel Opens Fab 9 in New Mexico
- AASE Technology Holding Co., Ltd. Reports Its Unaudited Consolidated Financial Results for the Fourth Quarter and the Full Year of 2025
- AAmkor Technology, current report on Form 8-K dated 9 February 2026
- AJCET Releases 2025 Annual Report, Posts Record-High Full-Year Revenue and Higher Profit Before Tax
- AASMPT Announces 2025 Annual Results AI-Driven Structural Growth Underpins Group Performance
- BThe Great AI Silicon Shortage
- ATSMC Debuts A13 Technology at 2026 North America Technology Symposium
- AAmkor Technology Breaks Ground on New Semiconductor Advanced Packaging and Test Campus in Arizona; Expands Investment to $7 Billion
- ANew JEDEC® SPHBM4 Standard Enables HBM4-Class Bandwidth on Organic Substrates
- ANVIDIA Hopper Architecture In-Depth
- AFoveros Direct 3D Technology Brief
- A[Tech Note] Hybrid Bonding: Evolving into a Foundational Technology for Improving Semiconductor Performance
- ATSMC, CoWoS technology page
- ATSMC 2025 Annual Report, chapter 5
- BNvidia’s Blackwell Reworked - Shipment Delays & GB200A Reworked Platforms
- BHybrid Bonding Process Flow - Advanced Packaging Part 5
- ATSMC 2022 Annual Report, page 97
- AQ2 2024 Taiwan Semiconductor Manufacturing Co Ltd Earnings Call (Chinese, English) — edited transcript
- AQ3 2025 Taiwan Semiconductor Manufacturing Co Ltd Earnings Call (Chinese, English) — edited transcript
- AQ2 2026 Taiwan Semiconductor Manufacturing Co Ltd Earnings Call (Chinese, English) — edited transcript
- AApplied Materials, Kinex integrated die-to-wafer hybrid bonding system product page
- ASupply Chain Explorer: Advanced Chips
- ATSMC Announces Additional $100 Billion Investment in Arizona
- AAmkor Technology, annual report on Form 10-K for the fiscal year ended 31 December 2025
- AQ3 2025 Taiwan Semiconductor Manufacturing Co Ltd Earnings Call (Chinese, English) — edited transcript
- AJCET Accelerates Strategic Shift Toward High-End Advanced Packaging, 2025 Advanced Packaging Revenue Hits Record High
- ATSMC 2025 Annual Report, chapter 5